Common Mistakes When Choosing Hurricane Coverage for Galveston Coastal Homes
Living on the Texas Gulf Coast means accepting a unique set of environmental risks that standard insurance models often fail to address. According to the National Weather Service, the Gulf Coast region experiences an average of 17 tropical storms or hurricanes annually, making comprehensive windstorm protection not just a recommendation but a financial necessity. Many homeowners in Texas City and surrounding areas assume their standard policy covers storm damage, only to discover devastating gaps when a storm hits. This guide outlines the critical errors to avoid, ensuring your property remains protected against the specific perils of the Galveston Bay area.
Understanding Windstorm Exclusions
One of the most frequent and costly errors involves misunderstanding the scope of windstorm coverage. In Texas, standard homeowners insurance policies often exclude wind and hail damage due to the high frequency of claims in coastal counties. This exclusion is particularly relevant for properties in Galveston County, where wind speeds can exceed 150 miles per hour during major events.
Homeowners must secure a specific Windstorm Insurance policy to cover these risks. Without this separate endorsement or policy, your home is effectively uninsured against the primary threat of the region. Brad Spurgeon Insurance Agency Inc. specializes in providing these essential Windstorm Insurance policies for Texas Gulf Coast homeowners. It is vital to verify that your policy explicitly includes wind and hail coverage, rather than assuming it is bundled by default.
Why Standard Policies Fall Short
Standard homeowners insurance is designed for inland risks. It typically covers fire, theft, and liability but explicitly lists wind and hail as exclusions in coastal zones. This structural separation exists because the risk profile for wind damage is significantly higher in areas like Texas City. If you do not have a dedicated windstorm policy, you are exposed to total financial loss for roof damage, siding loss, and structural integrity issues caused by high winds.
Navigating Percentage Deductibles
Another critical mistake is underestimating the impact of windstorm deductibles. Unlike standard homeowners policies that often have a flat dollar deductible, windstorm deductibles are typically calculated as a percentage of your home's insured value. This percentage can range from 1% to 5% or more, depending on the carrier and your specific location.
For a home insured at $500,000, a 2% windstorm deductible equals $10,000 out of pocket before coverage begins. Many homeowners are shocked by this amount when filing a claim. It is essential to understand how your deductible is calculated and to ensure you have the liquidity to cover it. Our agency provides detailed insurance quotes that clearly outline these deductible structures so you can make an informed decision.
Calculating Your Exposure
When comparing policies, look beyond the premium cost. A lower premium often correlates with a higher deductible percentage. You must balance the monthly cost with your ability to pay the deductible in the event of a loss. Understanding this trade-off is key to maintaining financial stability after a storm. We recommend reviewing your policy review options to adjust these parameters based on your current financial situation.
The Flood Insurance Gap
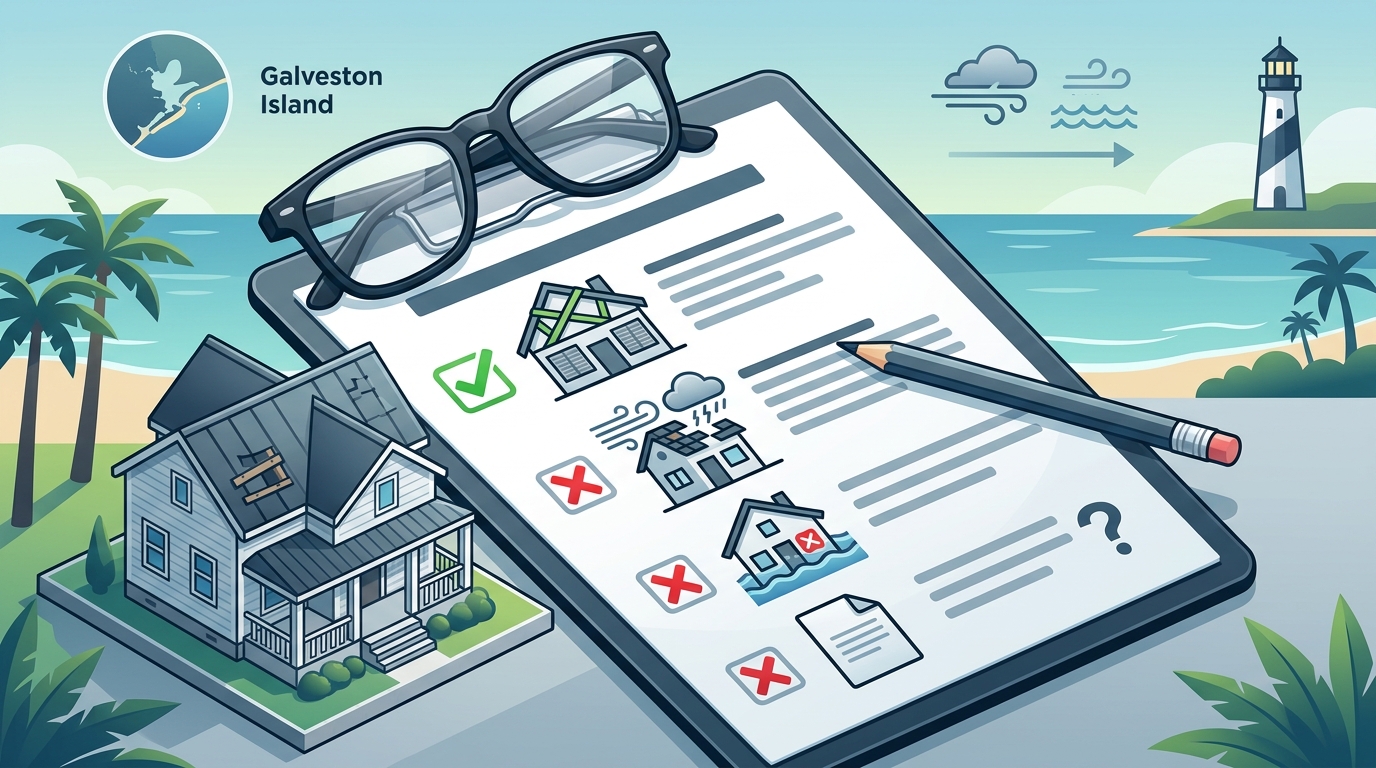
Perhaps the most dangerous misconception is that windstorm coverage includes flood damage. This is false. Windstorm insurance covers damage caused by wind, such as roof loss or broken windows. Flood insurance covers damage caused by rising water, including storm surge and heavy rainfall accumulation.
Galveston County is highly susceptible to storm surge due to its low elevation and proximity to the Gulf of Mexico. According to FEMA, over 90% of natural disasters are related to water, and flood damage is not covered by standard homeowners or windstorm policies. You must purchase a separate Flood Insurance policy to protect against this specific risk.
Understanding Storm Surge
Storm surge is the abnormal rise of water generated by a storm, primarily from winds pushing water onshore. This phenomenon can cause catastrophic damage that wind policies do not address. Even if your home is not in a designated high-risk flood zone, it can still experience flooding during a major hurricane. We offer comprehensive flood insurance quotes to help you assess your specific risk level and secure appropriate coverage.
Valuation Methodology Errors
Homeowners often make the mistake of insuring their home for its market value rather than its replacement cost. Market value includes the land, location premium, and market trends, which are irrelevant if your home is destroyed. Replacement cost is the amount required to rebuild your home with similar materials and craftsmanship at current construction prices.
Construction costs in Texas have risen significantly due to labor shortages and material inflation. Underinsuring your home can lead to a coinsurance penalty, where the insurance company reduces your payout if you do not maintain adequate coverage. It is crucial to get a professional home insurance quote that accurately reflects the current cost to rebuild your specific property.
Ensuring Adequate Coverage
Regularly update your coverage limits to reflect inflation and any renovations you have made. If you have added a pool, upgraded your kitchen, or expanded your living space, your replacement cost has increased. Failure to update your policy means you may not have enough funds to fully restore your home. Our team can help you conduct a thorough policy review to ensure your limits are current.
Neglecting Annual Policy Reviews
Insurance needs are not static. Changes in your home, your financial situation, or the local risk landscape require regular policy adjustments. Many homeowners set their insurance on autopilot and forget to review it until they need to file a claim. This neglect can lead to significant gaps in coverage or overpayment for services you no longer need.
We encourage all clients to schedule an annual policy review with our agency. This proactive approach ensures that your coverage aligns with your current needs and that you are aware of any changes in your premium or deductible. Regular reviews also provide an opportunity to discuss new products, such as our specialized Windstorm Insurance options.
Identifying Coverage Gaps
During a policy review, ask about additional coverages such as ordinance or law coverage, which pays for the increased cost of rebuilding to meet current building codes. This is particularly important in older neighborhoods in Texas City where building codes have evolved significantly. We also offer Condo Insurance and Landlord Insurance with specific endorsements for coastal properties.
Mistakes During the Claim Process
Even with perfect coverage, homeowners can make critical errors when filing a claim. One common mistake is attempting to make temporary repairs without documenting the damage first. Photographs and videos of the damage before any repairs are made are essential for a successful claim.
Another error is hiring contractors before consulting with your insurance adjuster. While you have the right to choose your contractor, coordinating with the adjuster first ensures that the scope of work is approved and covered. Our agency provides claim reporting assistance to help guide you through this complex process. We also offer free consultations to discuss your specific situation.
Documentation and Communication
Maintain a detailed log of all communications with your insurance company and contractors. Keep receipts for any temporary repairs or additional living expenses. Clear documentation strengthens your position during the settlement negotiation. If you need help understanding your online documents or policy details, our staff is available to assist you.
Key Takeaways
- Standard homeowners policies in Texas often exclude wind and hail damage, requiring a separate Windstorm Insurance policy.
- Windstorm deductibles are typically a percentage of the home's insured value, not a flat dollar amount.
- Flood insurance is a separate policy and does not cover wind damage or storm surge.
- Insure your home for replacement cost, not market value, to avoid coinsurance penalties.
- Brad Spurgeon Insurance Agency Inc. has served the Texas Gulf Coast since 1986, providing specialized coverage.
- Regular policy reviews are essential to keep coverage limits aligned with inflation and home improvements.
- Document all damage before making repairs and coordinate with your adjuster before hiring contractors.
Frequently Asked Questions
Does standard homeowners insurance cover wind damage in Galveston?
No, standard homeowners insurance policies in Texas typically exclude wind and hail damage. You must purchase a separate Windstorm Insurance policy to be covered for these risks.
What is the difference between windstorm and flood insurance?
Windstorm insurance covers damage caused by high winds, such as roof loss or broken windows. Flood insurance covers damage caused by rising water, including storm surge and rainfall accumulation. Both are necessary for comprehensive protection.
How is the windstorm deductible calculated?
The windstorm deductible is usually a percentage of your home's insured value, ranging from 1% to 5% or more. This amount is paid out of pocket before your insurance coverage begins.
Why do I need flood insurance if I am not in a flood zone?
Storm surge and heavy rainfall can cause flooding in areas outside designated high-risk flood zones. Standard policies do not cover flood damage, so a separate flood insurance policy is essential for all coastal homeowners.
How often should I review my insurance policy?
We recommend reviewing your insurance policy annually to ensure your coverage limits reflect current construction costs and any changes to your home or financial situation.
Can I get a quote for both windstorm and flood insurance?
Yes, we offer comprehensive quotes for both Windstorm Insurance and Flood Insurance. Contact us to get a free consultation and tailored coverage options for your home.
What should I do if I need to file a claim?
Document the damage with photos and videos before making any repairs. Contact your insurance company to report the claim and consult with our agency for guidance on the process.
Secure Your Home Today
Protecting your Galveston coastal home requires more than just a standard policy. You need specialized Windstorm Insurance and Flood Insurance to address the unique risks of the Texas Gulf Coast. Brad Spurgeon Insurance Agency Inc. has been serving Texas City and surrounding communities since 1986, providing expert guidance and comprehensive coverage. Do not wait for a storm to reveal the gaps in your protection. Contact us today to get a free consultation and ensure your home is fully protected.
Get a Free Insurance Quote now to secure your peace of mind.