Common Windstorm Insurance Mistakes That Increase Your Coastal Premiums
Living on the Texas Gulf Coast means accepting the reality of severe weather. According to recent industry data, wind and hail claims account for a significant percentage of all property damage in coastal regions, with some estimates suggesting that over 60% of home insurance claims in Texas are weather-related. This high risk profile directly influences how carriers price your policy. Many homeowners unknowingly trigger premium spikes by making critical errors in their coverage selection. Understanding these mistakes is the first step toward protecting your wallet and your home.
Ignoring the Windstorm Deductible
One of the most common and costly errors homeowners make is focusing solely on the monthly premium while ignoring the deductible structure. In Texas, windstorm deductibles are often calculated as a percentage of the dwelling coverage limit, typically ranging from 2% to 5%. This means that if your home is insured for $300,000 with a 2% wind deductible, you would be responsible for $6,000 out of pocket before your insurance kicks in.
Many homeowners assume their standard deductible applies to wind damage, which is rarely the case in coastal zones. When a storm hits, the difference between a $500 standard deductible and a 2% wind deductible can be tens of thousands of dollars. This is why understanding the Windstorm Insurance policy details is crucial. A lower premium often comes with a higher percentage deductible, which can be financially devastating if a storm occurs. Always calculate the potential out-of-pocket cost based on your home's insured value, not just the monthly bill.
Underestimating Replacement Cost
Another critical mistake is insuring your home for its market value rather than its replacement cost. Market value includes the land, location, and market trends, which do not help you rebuild your home after a total loss. Replacement cost covers the materials and labor required to construct your home to its pre-loss condition. Inflation in construction materials and labor costs has surged in recent years, making accurate valuation more important than ever.
If you underinsure your home, you may face a coinsurance penalty. This penalty reduces your claim payout if you do not maintain coverage equal to a specified percentage of your home's replacement cost. For example, if you are required to carry 80% of the replacement value but only carry 70%, your claim will be reduced proportionally. Ensure your policy reflects current construction costs in Texas City and surrounding Gulf Coast communities. You can review your current coverage limits by visiting our Policy Review service.
Skipping Flood Coverage
Perhaps the most dangerous misconception is believing that standard home insurance covers flood damage. It does not. Flood insurance is a separate policy that covers damage from rising water, including storm surge, heavy rain, and overflowing bodies of water. Standard homeowners policies explicitly exclude this type of damage.
Many homeowners in coastal areas assume they are safe because they are not in a designated high-risk flood zone. However, data shows that a significant portion of flood claims come from moderate-to-low risk areas. With climate change increasing the frequency of severe weather events, the risk is no longer limited to low-lying areas. Without a separate flood policy, you could be left with millions in repair costs. We offer comprehensive Flood Insurance Quotes to ensure you are fully protected against water damage.
Choosing the Wrong Carrier
Not all insurance carriers are willing or able to write windstorm coverage in high-risk coastal zones. Some major national carriers have exited the Texas market or have severely restricted their underwriting appetite for Gulf Coast properties. If you rely on a carrier that has pulled out of the region, you may find yourself without coverage when you need it most.
It is essential to work with an agency that has access to a diverse panel of carriers, including those specializing in high-risk coastal insurance. Brad Spurgeon Insurance Agency Inc. has served the Texas Gulf Coast since 1986, maintaining relationships with multiple carriers that specialize in wind and hail coverage. This allows us to find the best rates and coverage options for our clients. You can learn more about our Insurance Carriers and our commitment to service on our About page.
Neglecting Policy Reviews
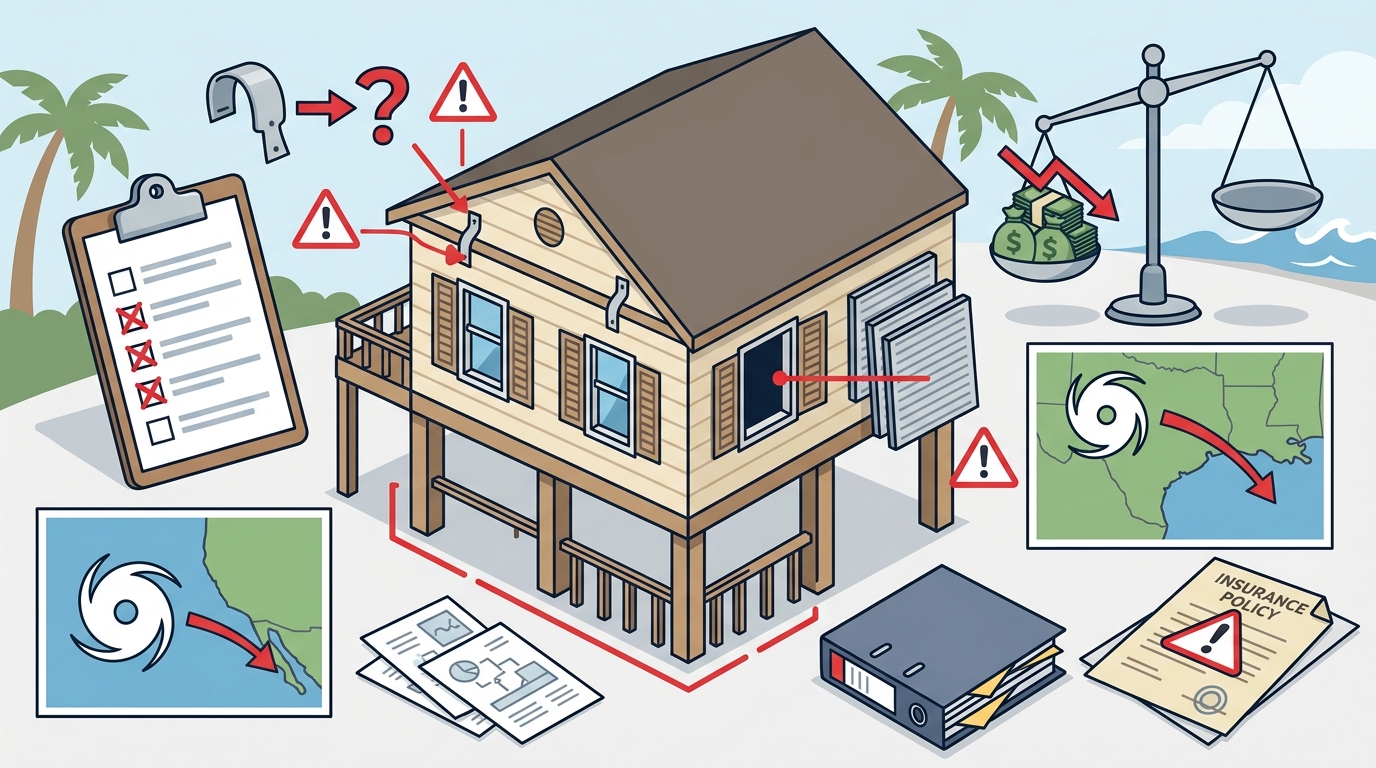
Insurance needs change over time. Home renovations, new roofs, and increased personal property values can all impact your coverage requirements. Many homeowners set their policy and forget about it for years. This neglect can lead to gaps in coverage or unnecessary premiums if your home's risk profile has decreased.
Regular policy reviews ensure that your coverage keeps pace with your home's value and your personal needs. We recommend reviewing your policy annually or after any significant home improvement. Our team can help you identify opportunities to save money while maintaining robust protection. Schedule a Free Consultation to discuss your current coverage and identify any potential gaps.
Key Takeaways
- Wind Deductibles are Percentage-Based: Unlike standard deductibles, wind deductibles are often a percentage of your dwelling coverage, leading to higher out-of-pocket costs during storms.
- Replacement Cost is Critical: Insure your home for the cost to rebuild, not its market value, to avoid coinsurance penalties and ensure adequate funds for reconstruction.
- Flood Insurance is Separate: Standard home policies do not cover flood damage. A separate flood policy is essential for any coastal homeowner, regardless of flood zone designation.
- Carrier Availability Varies: Many national carriers have restricted or exited the Texas coastal market. Working with a specialized agency ensures access to reliable coverage.
- Regular Reviews Save Money: Annual policy reviews can identify coverage gaps and potential savings opportunities as your home and personal circumstances change.
- Brad Spurgeon Insurance Agency Inc. has served the Texas Gulf Coast since 1986. Our third-generation family agency provides personalized service and expert guidance.
- Proactive Management is Key: Utilizing online services for payments and claims can streamline the process and reduce stress during critical times.
Frequently Asked Questions
What is a windstorm deductible?
A windstorm deductible is a specific amount you pay out of pocket for wind and hail damage, often calculated as a percentage of your home's insured value rather than a flat fee.
Does home insurance cover flood damage?
No, standard homeowners insurance policies do not cover flood damage. You need a separate flood insurance policy to be protected against water damage from rising water.
Why do coastal insurance premiums increase?
Premiums increase due to higher risk profiles, increased construction costs, and the frequency of severe weather events in the region. Carriers adjust rates to reflect the potential for large claims.
How often should I review my insurance policy?
You should review your policy annually or after any significant home improvement, such as a new roof or major renovation, to ensure your coverage remains adequate.
What is the WPI-8 form?
The WPI-8 is a specific policy form used in Texas for windstorm and hail coverage. It outlines the terms, conditions, and exclusions specific to wind damage protection.
Can I get a quote online?
Yes, you can get a quote online through our website. We offer easy-to-use forms for home, flood, and windstorm insurance quotes to help you get started quickly.
What services does Brad Spurgeon Insurance Agency offer?
We offer a wide range of services including home, flood, windstorm, auto, and business insurance, as well as claim reporting, payment processing, and policy reviews.
Protect Your Home Today
Don't let common insurance mistakes leave you vulnerable to financial ruin. Whether you need a new Home Insurance Quote, a Flood Insurance Quote, or a review of your current Windstorm Insurance policy, Brad Spurgeon Insurance Agency Inc. is here to help. Our team of experts is dedicated to providing personalized service and competitive rates for homeowners across the Texas Gulf Coast. Contact us today at (409) 945-4746 or visit our Contact page to schedule your free consultation. Secure your peace of mind with coverage you can trust.