Common Windstorm Insurance Application Mistakes That Prevent Approval
Securing windstorm insurance in Texas is a critical step for homeowners living along the Gulf Coast, yet the approval process is notoriously strict. Private Windstorm data indicates that nearly 40% of initial applications are delayed or denied due to avoidable documentation errors. These mistakes often stem from a misunderstanding of state-specific regulations and carrier requirements. This guide outlines the most frequent pitfalls and provides actionable steps to ensure your application moves forward smoothly.
Understanding the WPI-8 Certificate
The WPI-8 certificate is the cornerstone of any Texas windstorm application. This document, issued by a licensed roof inspector, certifies the condition and age of your roof. Without a valid WPI-8, most carriers will not bind coverage. A common mistake is submitting an expired certificate or one that does not match the current property details. (Home Flood amp Windstorm)
The WPI-8 certificate is a standardized form used to verify roof compliance with state windstorm regulations. It must be signed by a licensed inspector and submitted directly to the insurance carrier. If the roof is older than 10 years, carriers often require a more recent inspection to confirm it can withstand high winds. Ensuring your certificate is current and accurate is the first step toward approval. (Home Insurance Flood Windstorm)
Roof Certification and Age Misstatements
Homeowners frequently misstate the age of their roof on the application form. If the declared age differs from the WPI-8 certificate, the application will likely be flagged for review. This discrepancy can lead to significant delays as the carrier requests clarification or a new inspection. (Windstorm Insurance Inspections Brad)
Another error is failing to disclose recent roof repairs. Even minor repairs can affect the roof's wind resistance rating. Carriers need a complete picture of the roof's history to assess risk accurately. Be transparent about any work done, no matter how small. This honesty prevents future disputes and ensures your policy reflects the true condition of your home.
Inaccurate Construction and Elevation Data
The construction type and elevation of your home are critical factors in windstorm underwriting. Misclassifying the construction material, such as listing a frame home as masonry, can result in immediate denial. Carriers use this data to calculate the potential damage from wind and hail.
Elevation data is equally important. Homes in flood zones or low-lying areas may require additional endorsements or higher deductibles. Incorrect elevation data can lead to underpricing the risk, which carriers will correct by increasing premiums or denying coverage. Verify your home's elevation with a professional survey if you are unsure. Accurate data helps your agent find the best carrier for your specific property profile.
Underestimating Coverage Needs
Many homeowners apply for coverage based on their mortgage balance rather than the full replacement cost of their home. This is a critical error. Windstorm policies often have separate deductibles for wind and hail, which can significantly impact out-of-pocket costs after a storm.
Replacement cost coverage ensures you can rebuild your home with similar materials and labor costs. If you underinsure, you may face a substantial gap in funds after a claim. Review your policy limits annually to ensure they keep pace with construction costs in your area. This proactive approach prevents coverage gaps when you need them most.
Ignoring Past Claim History
Your claims history is a major factor in underwriting decisions. Failing to disclose past wind or water damage claims can lead to policy cancellation or non-renewal. Carriers have access to industry databases that track all claims filed within the last seven years.
Even if you paid for a previous claim out of pocket, it may still appear in your history if a report was filed. Be upfront about any past incidents. Your agent can help explain these claims to the carrier and demonstrate how you have mitigated risk since then. Transparency builds trust and can sometimes lead to more favorable terms.
Timing and Documentation Delays
Timing your application correctly is crucial, especially during hurricane season. Carriers often experience backlogs during peak periods, which can delay policy issuance. Submitting your application well in advance of any potential storm or policy expiration date is essential.
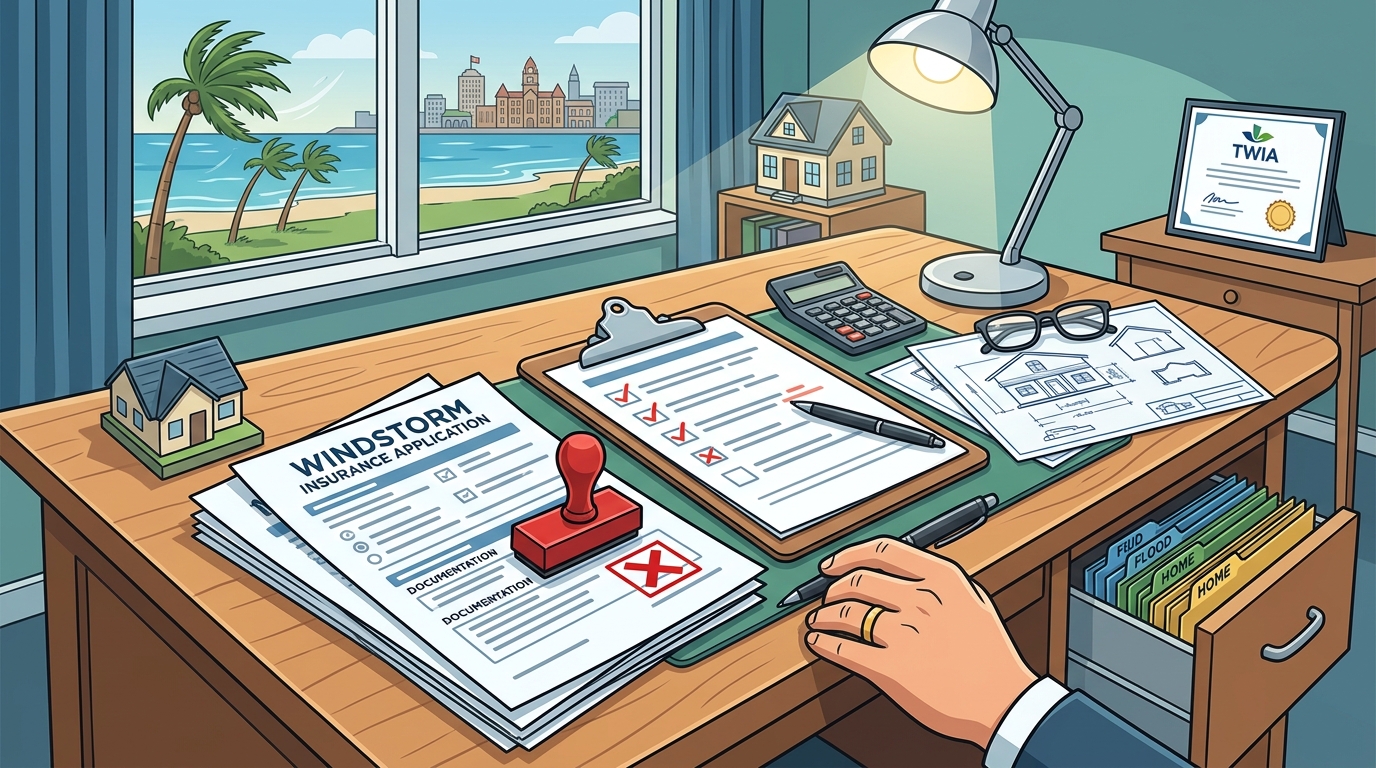
Another common mistake is incomplete documentation. Missing photos, surveys, or inspector reports can halt the underwriting process. Ensure you have all required documents ready before starting the application. This preparation speeds up the review process and reduces the likelihood of requests for additional information.
Key Takeaways
- The WPI-8 certificate is mandatory for Texas windstorm coverage and must be current.
- Roof age must match the inspector's report exactly to avoid delays.
- Construction type and elevation data must be verified for accuracy.
- Replacement cost coverage is essential for adequate protection.
- Disclose all past claims, even if paid out of pocket.
- Submit applications early to avoid hurricane season backlogs.
- Brad Spurgeon Insurance Agency has served the Gulf Coast since 1986.
Frequently Asked Questions
What is the WPI-8 certificate?
The WPI-8 certificate is a document issued by a licensed roof inspector that certifies the condition and age of a roof for windstorm insurance purposes.
How old can my roof be for windstorm insurance?
Roofs older than 10 years often require a recent inspection to prove they can withstand high winds. Some carriers may have stricter age limits.
Do I need flood insurance if I have windstorm coverage?
Yes, windstorm insurance does not cover flood damage. Separate flood insurance is required for properties in flood zones.
How long does windstorm insurance approval take?
Approval can take several days to weeks, depending on the carrier and the completeness of your documentation.
Can I get windstorm insurance if I have a past claim?
Yes, but it may affect your premium or coverage terms. Full disclosure is essential for approval.
What is the difference between replacement cost and actual cash value?
Replacement cost covers the full cost to rebuild your home, while actual cash value accounts for depreciation.
How often should I review my windstorm policy?
Review your policy annually to ensure coverage limits keep pace with construction costs and property changes.
Who can inspect my roof for the WPI-8?
Only a licensed roof inspector authorized by the Texas Department of Insurance can issue a valid WPI-8 certificate.
Get Your Windstorm Coverage
Navigating the complexities of windstorm insurance requires expertise and attention to detail. Brad Spurgeon Insurance Agency Inc. has been serving Texas City and the Gulf Coast since 1986. We specialize in helping homeowners secure the coverage they need. Contact us today for a free consultation and quote. Visit our Home Insurance Quote page to get started. Our team is ready to help you protect your home with confidence.