Comparing Private Windstorm Insurance Options for Hurricane Coverage in Galveston
Homeowners in the Texas Gulf Coast face unique risks that standard policies simply cannot address. Private windstorm insurance is a specialized policy designed to cover wind and hail damage to your home, which is typically excluded from standard homeowners insurance in high-risk coastal zones. According to recent industry data, over 60% of hurricane-related property claims in Texas involve wind damage that falls outside traditional coverage limits. This gap leaves many homeowners financially vulnerable when storms strike. Understanding the differences between available options is critical for protecting your most significant asset. (Home Insurance Flood Windstorm)
Why Standard Policies Fail in Coastal Zones
Most homeowners assume their standard policy covers all weather-related damage. This is a dangerous misconception in Galveston County. Standard homeowners insurance policies often contain specific exclusions for windstorms and hail. These exclusions are particularly prevalent in counties designated as high-risk for hurricane activity.
When a hurricane makes landfall, the resulting wind damage can be catastrophic. Without a separate windstorm policy, you are responsible for every dollar of repair costs. This includes roof damage, siding loss, and structural failures. The financial impact can be devastating for families who have not planned for such events. Federal emergency management reports indicate that wind is the primary cause of property damage during tropical cyclones.
Brad Spurgeon Insurance Agency has served the Texas City community since 1986. We understand that protecting your home requires more than just a basic policy. We specialize in helping homeowners navigate the complex landscape of coastal insurance. Our goal is to ensure you have the right coverage before the storm hits.
The WPI-8 Certificate and Coverage Gaps
One of the most critical documents in Texas windstorm insurance is the WPI-8 Certificate. This certificate outlines the specific terms and conditions of your windstorm coverage. It serves as proof that you have met the mandatory windstorm insurance requirements set by the state.
Understanding the WPI-8 is essential for comparing different insurance options. The certificate details your deductible, coverage limits, and any exclusions. It also specifies whether the policy covers wind, hail, or both. Some policies may have higher deductibles for hurricane events. This means you pay a larger percentage of the claim cost when a named storm occurs.
We provide a comprehensive WPI-8 Certificate Guide to help you interpret these documents. Our team can explain how your specific deductible applies to different types of weather events. This clarity is vital for budgeting your potential out-of-pocket costs.
Comparing Private Windstorm Options
Choosing the right windstorm insurance requires comparing several key factors. Not all policies are created equal. Some offer broader coverage, while others may be more cost-effective for specific property types. Below is a comparison of the primary options available to Galveston homeowners.
| Policy Type | Coverage Scope | Deductible Structure | Best For |
|---|---|---|---|
| Standalone Windstorm | Wind and hail damage only | Percentage-based (hurricane) or flat rate | Homeowners with existing homeowners coverage |
| Windstorm Included Home Policy | Comprehensive home and wind coverage | Combined deductible structure | Those seeking simplified billing and unified claims |
| Flood Insurance | Water damage from rising waters | Flat rate per coverage unit | Properties in flood zones or low-lying areas |
| Umbrella Policy | Liability coverage above primary limits | High limit excess | High-net-worth individuals seeking extra protection |
The Windstorm Included Home Policy is a newer option for Texas Gulf Coast homeowners. This policy combines windstorm coverage with standard homeowners insurance. It simplifies the renewal process and ensures that your wind coverage is not overlooked. For many homeowners, this integrated approach offers peace of mind and administrative ease.
However, a standalone windstorm policy may be necessary if your primary insurer does not offer wind coverage. In this case, you must coordinate between two different carriers. This can complicate the claims process if damage is caused by both wind and water. Our agency helps you manage these relationships to ensure seamless coverage.
Key Coverage Features to Evaluate
When comparing quotes, look beyond the premium price. The value of your policy lies in its coverage features. Here are the critical elements to scrutinize.
Deductible Types
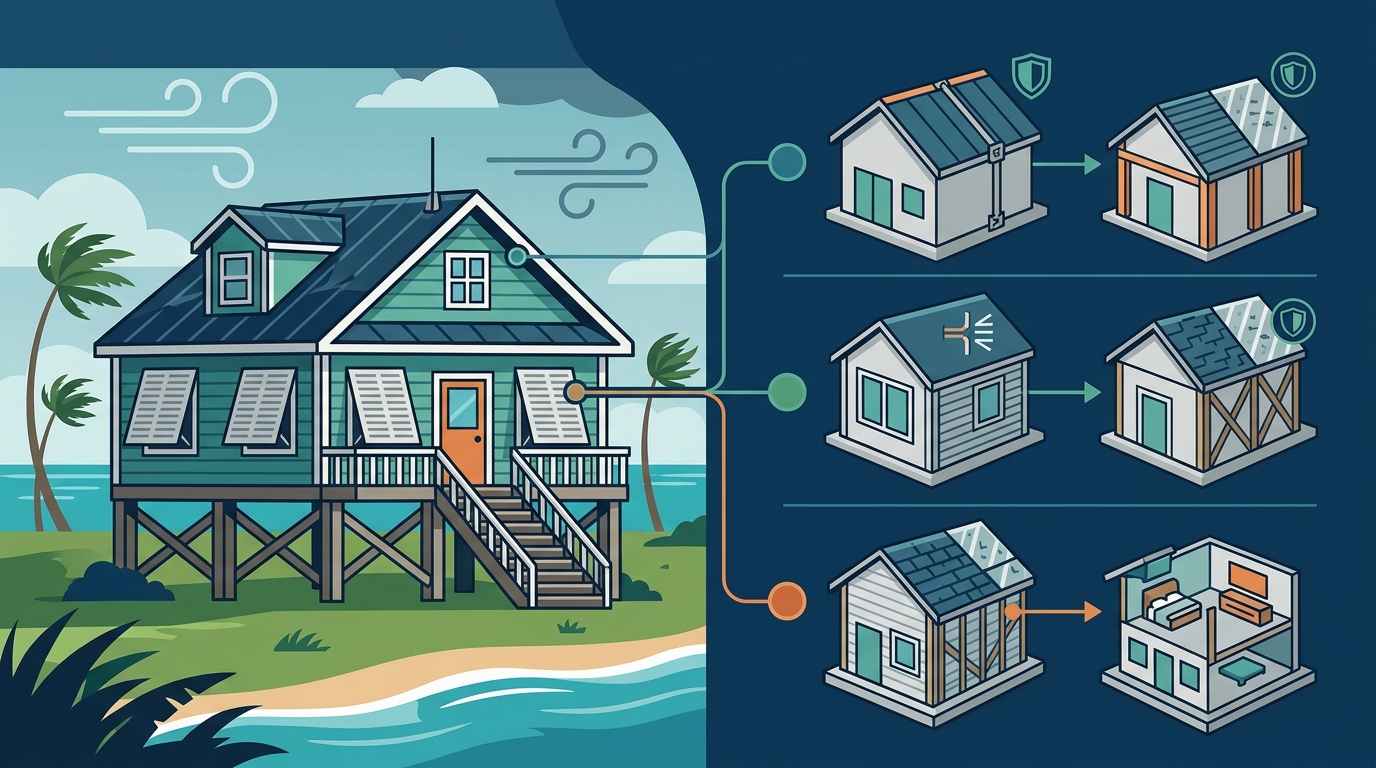
Windstorm deductibles are often percentage-based. For example, a 2% deductible on a $500,000 home means you pay $10,000 before insurance kicks in. Some policies offer a flat dollar deductible for non-hurricane wind events. Understanding this distinction is crucial for financial planning.
Replacement Cost vs. Actual Cash Value
Replacement cost coverage pays to rebuild your home with new materials. Actual cash value accounts for depreciation. In a market where construction costs are rising, replacement cost coverage is essential. It ensures you have enough funds to restore your property to its pre-storm condition.
Code Upgrade Coverage
Building codes change over time. If your home is damaged, current codes may require upgrades during reconstruction. Code upgrade coverage pays for these additional costs. Without it, you may have to pay for these improvements out of pocket.
We recommend reviewing your policy annually to ensure your coverage limits keep pace with inflation and local construction costs. Policy Review services are available to help you assess your current protection levels.
Navigating the Claims Process
The true test of an insurance provider is how they handle claims. When a hurricane strikes, time is of the essence. A responsive agency can make a significant difference in the speed and fairness of your settlement.
Brad Spurgeon Insurance Agency prides itself on being in the business of helping people. We are not just a quote generator. We are your advocate throughout the claims process. From the initial report to the final settlement, we guide you through every step.
Our Report a Claim service is designed to be quick and efficient. We help you document the damage accurately and communicate with your carrier effectively. This support reduces stress and ensures that your claim is processed without unnecessary delays.
External data suggests that homeowners who work with experienced agents are more likely to receive fair settlements. Agents understand the nuances of policy language and can identify coverage items that homeowners might miss. This expertise is invaluable during the chaotic aftermath of a storm.
Key Takeaways
- Standard homeowners policies often exclude wind and hail damage in high-risk coastal zones like Galveston.
- Private windstorm insurance is mandatory for many lenders in Texas Gulf Coast communities.
- The WPI-8 Certificate is the primary document outlining your windstorm coverage terms and deductibles.
- Windstorm deductibles are frequently percentage-based, which can result in high out-of-pocket costs.
- The Windstorm Included Home Policy offers a simplified alternative to managing separate policies.
- Flood insurance is separate from windstorm coverage and is required for properties in designated flood zones.
- Brad Spurgeon Insurance Agency has served the Texas Gulf Coast since 1986 with a focus on personalized service.
Frequently Asked Questions
Do I need separate windstorm insurance if I have homeowners insurance?
In many high-risk areas of Texas, standard homeowners policies exclude wind and hail damage. You will likely need a separate windstorm policy or a policy that explicitly includes wind coverage to ensure you are protected.
What is the WPI-8 Certificate?
The WPI-8 Certificate is a document issued by your insurance carrier that proves you have windstorm insurance. It details your coverage limits, deductibles, and effective dates. It is often required by lenders and local authorities.
How is the windstorm deductible calculated?
Windstorm deductibles are often calculated as a percentage of your dwelling coverage limit. For example, a 2% deductible on a $400,000 home would be $8,000. Some policies may have a flat deductible for non-hurricane events.
What is the difference between windstorm and flood insurance?
Windstorm insurance covers damage caused by wind and hail, such as roof damage or broken windows. Flood insurance covers damage from rising water, such as storm surge or heavy rainfall flooding. These are two distinct types of coverage.
Can I get a quote for both windstorm and flood insurance?
Yes. We offer comprehensive quotes for both windstorm and flood insurance. This allows you to compare options and ensure you have complete protection against all coastal risks.
How long does it take to process a windstorm claim?
Claim processing times vary depending on the extent of the damage and the number of claims filed. However, working with an experienced agency like Brad Spurgeon Insurance Agency can help expedite the process through efficient communication and documentation.
Does the Windstorm Included Home Policy cover all risks?
The Windstorm Included Home Policy combines wind coverage with standard homeowners insurance. However, it typically does not cover flood damage. You may still need separate flood insurance for complete protection.
Secure Your Coverage Today
Do not wait for the next hurricane to realize your coverage is inadequate. Protect your home and your family with the right insurance. Brad Spurgeon Insurance Agency is here to help you navigate your options.
Contact us today for a free consultation. We will help you compare private windstorm insurance options and find the policy that best fits your needs. Visit our Quotes page to get started.