Essential Deductible and Coverage Criteria for Private Windstorm Insurance Named Storm Claims
Navigating the aftermath of a named storm in the Texas Gulf Coast region demands immediate clarity on your policy's specific financial triggers. Data indicates that standard homeowners policies frequently exclude wind and hail damage, leaving property owners vulnerable to massive out-of-pocket expenses without specialized private windstorm coverage. Understanding the exact deductible structures and coverage criteria is not merely administrative; it is the primary determinant of your financial recovery speed and total claim payout. This guide dissects the critical elements of windstorm insurance to ensure you are prepared for the next weather event. (Home Insurance Flood Windstorm)
Understanding Windstorm Coverage Basics
Windstorm insurance is a specialized policy type designed to cover damage caused by high winds, hail, and associated weather events. Unlike standard homeowners insurance, which often contains broad exclusions for wind-related damage in high-risk coastal areas, private windstorm policies fill this critical gap. For homeowners in Texas City and the broader Gulf Coast, this coverage is not optional; it is a fundamental requirement for financial stability.
Windstorm insurance provides coverage for property damage caused by wind events that are not included in standard homeowners policies. This distinction is vital because the cost of repairing a roof torn off by a hurricane can easily exceed $50,000. Without a dedicated windstorm policy, that entire cost falls on the homeowner. Brad Spurgeon Insurance Agency has served these communities since 1986, helping families navigate these complex waters with clarity and precision.
The core function of this insurance is to protect your physical structure and personal belongings from the direct force of the storm. This includes damage to siding, windows, doors, and the roof deck. It also extends to debris removal costs, which can be substantial after a major event. By securing a policy through a trusted local agency, you ensure that your coverage limits align with the current replacement cost of your home, not just its market value.
Deductible Types and Calculations
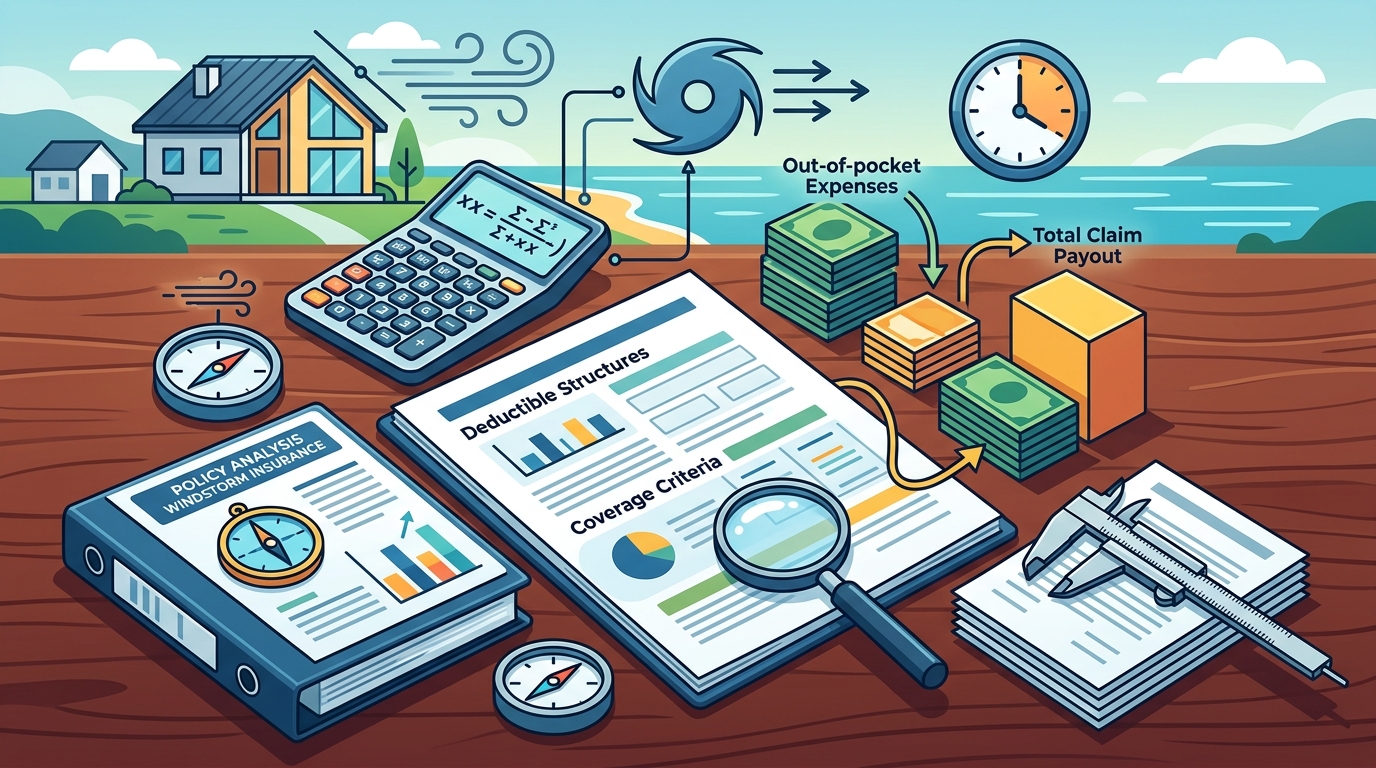
The deductible is the amount you pay out of pocket before your insurance coverage kicks in. In the context of windstorm insurance, deductibles are often higher and structured differently than those for standard homeowners claims. Understanding these structures is crucial for accurate financial planning.
Percentage-Based Deductibles
Most private windstorm policies utilize a percentage-based deductible. This is calculated as a specific percentage of your home's insured value. For example, if your home is insured for $300,000 and you have a 2% wind deductible, you would be responsible for the first $6,000 of the claim. This structure ensures that the deductible scales with the value of your property, preventing underinsurance in high-value markets.
Flat-Rate Deductibles
Some policies may offer a flat-rate deductible for wind and hail damage. This is a fixed dollar amount, such as $1,000 or $2,500, regardless of the home's value. While this may seem more affordable initially, it can be risky if your home's value has appreciated significantly. It is essential to review your policy declarations page to determine which type applies to your specific coverage.
Combined Wind/Hail Deductibles
Many insurers now use a combined deductible for wind and hail damage. This means that if a storm causes both wind and hail damage, you only pay one deductible, not two. This is a significant benefit for homeowners in areas prone to severe thunderstorms and hurricanes alike. Always confirm with your agent whether your policy includes this combined structure.
Defining Named Storms and Triggers
The definition of a "named storm" is the primary trigger for windstorm coverage. Not all wind damage is covered under a windstorm policy; the event must meet specific meteorological and legal criteria. This distinction prevents coverage for minor weather events while ensuring protection for major disasters.
A named storm is a tropical cyclone, hurricane, or tropical storm that has been officially named by the National Weather Service. Coverage typically activates when the storm reaches a specific wind speed threshold, often 39 miles per hour or higher. This threshold is critical because it distinguishes between a regular breeze and a destructive weather event.
The timing of the claim is also governed by the named storm declaration. If your policy is active when the storm is named, you are covered. However, if you wait until after the storm is named to purchase a policy, you will be excluded from coverage for that specific event. This is why proactive insurance management is essential. You cannot buy coverage after the storm has already formed.
Critical Coverage Criteria and Exclusions
Understanding what is covered is just as important as understanding the deductible. Private windstorm policies have specific criteria that must be met for a claim to be approved. These criteria are designed to ensure that the damage is directly caused by the wind event and not by other factors like poor maintenance or flooding.
Direct Physical Loss
Windstorm coverage typically applies only to direct physical loss. This means the wind must directly cause the damage. For example, if a tree falls on your house because the wind broke its branches, that is covered. However, if the tree was already dead and poorly maintained, the insurer may deny the claim based on lack of maintenance. The causal link between the wind and the damage must be clear and undeniable.
Flood Exclusions
It is crucial to understand that windstorm insurance does not cover flood damage. Flood insurance is a separate policy, often provided through the National Flood Insurance Program (NFIP) or private flood insurers. If water enters your home due to rising water levels, that is a flood claim, not a wind claim. Many homeowners mistakenly assume their windstorm policy covers water damage, leading to significant financial gaps.
Wind-Driven Rain
Some policies cover wind-driven rain damage. This occurs when high winds break windows or damage the roof, allowing rain to enter the home. The key is that the entry point must be caused by wind damage. If the rain enters through a pre-existing leak, it is not covered. This nuance is often a point of contention in claims, so thorough documentation is vital.
The Claim Process and Documentation
Filing a claim for windstorm damage requires a systematic approach. The speed and accuracy of your documentation can significantly impact the outcome of your claim. Working with an experienced local agency like Brad Spurgeon Insurance Agency can streamline this process.
Immediate Safety and Documentation
First, ensure the safety of your family and property. Use tarps to cover roof damage to prevent further water intrusion. Take extensive photos and videos of all damage before making any temporary repairs. This visual evidence is critical for your adjuster to assess the extent of the loss. Do not discard damaged items until the adjuster has seen them.
Contacting Your Agency
Once it is safe to do so, contact your insurance agency immediately. Brad Spurgeon Insurance Agency offers a dedicated claim reporting service to ensure your claim is processed quickly. Provide your policy number, a detailed description of the damage, and the date and time of the event. Your agent will guide you through the next steps, including scheduling an adjuster inspection.
The Adjuster Inspection
The insurance adjuster will inspect your property to determine the cause and extent of the damage. They will compare their findings to your policy terms and deductible. Be present during the inspection to point out all areas of damage. Provide your documentation and photos to support your claim. If you disagree with the adjuster's findings, you have the right to request a re-inspection or appeal the decision.
Key Takeaways
- Windstorm Deductibles are Percentage-Based: Most policies use a percentage of your home's insured value, not a flat rate, which scales with your property's worth.
- Named Storm Definition is Critical: Coverage only applies if the policy is active when the storm is officially named by the National Weather Service.
- Flood is Separate: Windstorm insurance does not cover flood damage; a separate flood policy is required for water intrusion from rising water.
- Direct Physical Loss Requirement: The wind must directly cause the damage; pre-existing conditions or poor maintenance can lead to claim denials.
- Proactive Policy Management: Do not wait until a storm is named to purchase coverage; it is too late for that specific event.
- Documentation is Key: Extensive photos and videos of damage before repairs are essential for a successful claim.
- Local Agency Expertise: Working with a local agency like Brad Spurgeon Insurance Agency ensures you understand your specific policy criteria and claim rights.
Frequently Asked Questions
What is the difference between windstorm and homeowners insurance?
Standard homeowners insurance often excludes wind and hail damage in high-risk coastal areas. Windstorm insurance is a specialized policy that fills this gap, providing coverage for damage caused by high winds and hail.
How is a windstorm deductible calculated?
Windstorm deductibles are typically calculated as a percentage of your home's insured value. For example, a 2% deductible on a $300,000 home would be $6,000. Some policies may offer flat-rate deductibles, so check your declarations page.
Does windstorm insurance cover flood damage?
No, windstorm insurance does not cover flood damage. Flood damage requires a separate flood insurance policy. Windstorm coverage is limited to damage directly caused by wind, such as roof loss or broken windows.
What is a named storm?
A named storm is a tropical cyclone, hurricane, or tropical storm that has been officially named by the National Weather Service. Coverage typically activates when the storm reaches a specific wind speed threshold, often 39 mph or higher.
Can I buy windstorm insurance after a storm is named?
No, you cannot purchase windstorm insurance after a storm has been named. Coverage must be in effect before the storm is officially named to be eligible for claims related to that event.
What should I do immediately after a windstorm?
Ensure your safety first, then take photos and videos of all damage. Make temporary repairs to prevent further damage, such as tarping the roof. Contact your insurance agency as soon as possible to start the claim process.
How long does the claim process take?
The timeline varies depending on the extent of the damage and the number of claims filed. However, working with a local agency can help expedite the process by ensuring all documentation is complete and accurate from the start.
Secure Your Coverage Today
Do not wait for the next storm to test your coverage. Protect your home and family with a comprehensive windstorm insurance policy tailored to your specific needs. Brad Spurgeon Insurance Agency has been serving the Texas Gulf Coast since 1986, providing expert guidance and reliable coverage. Contact us today for a free consultation and quote. Visit our Home Insurance Quote page to get started. You can also explore our Flood Insurance Quote options to ensure you have complete protection. For more information about our agency, visit our About page. If you have existing questions, our Blog offers valuable insights into insurance topics. Contact us at (409) 945-4746 or visit our office at 1118 14th Street North, Texas City, Texas 77590.