What Exactly Does My Windstorm Policy Cover When a Named Hurricane Hits?
When a named hurricane strikes the Texas Gulf Coast, your windstorm policy typically covers direct physical damage to your home's structure and contents caused by high winds. This coverage is distinct from flood insurance, which handles water damage. At Brad Spurgeon Insurance Agency, we help homeowners in Galveston and Texas City understand these specific boundaries to ensure they are not caught off guard by a storm event.
The Scope of Wind Damage Coverage
Windstorm insurance is a specialized property insurance policy designed to protect against damage caused by high winds, including those from hurricanes and tropical storms. In Texas, many standard homeowners policies exclude wind damage, requiring a separate windstorm policy. This separation is critical because the perils covered by a standard HO-3 policy do not extend to the high-velocity winds that characterize a named hurricane.
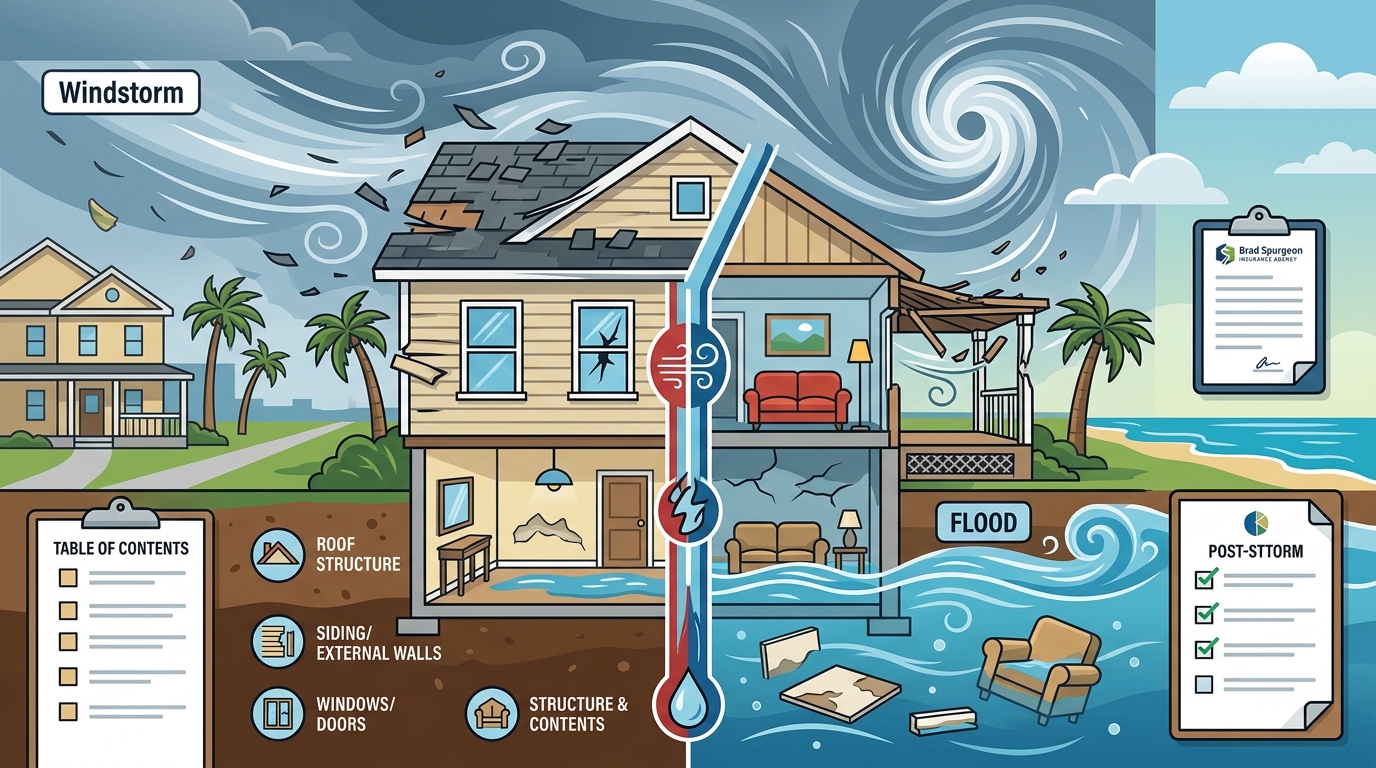
When a named storm makes landfall, the policy responds to the physical force of the wind. This includes damage to the roof, siding, windows, and doors. If a tree falls on your house due to high winds, that is a covered wind event. However, if the tree falls because the ground was saturated and unstable from rain, the classification of the cause becomes a complex issue that requires careful documentation.
Structural vs. Contents Protection
Your windstorm policy generally splits coverage into two main categories: the dwelling itself and your personal property. The dwelling coverage protects the physical structure, including the roof, walls, and foundation if wind-driven debris causes damage. Personal property coverage protects items inside the home, such as furniture, electronics, and clothing, if they are damaged by wind or wind-driven debris.
The Critical Exclusion of Flood Damage
The most common misunderstanding among Gulf Coast homeowners is the belief that windstorm insurance covers all damage resulting from a hurricane. It does not. Flood insurance is a separate policy, typically purchased through the National Flood Insurance Program (NFIP) or private carriers. If water enters your home through a door or window that was blown open by wind, that damage is covered by your windstorm policy. However, if water enters through the roof or foundation due to rising water or heavy rain, it is considered flood damage and is excluded from windstorm coverage.
This distinction is vital for homeowners in Galveston and surrounding areas. A single hurricane can cause both wind and flood damage. If you only have windstorm insurance, you will be responsible for the cost of repairing any water damage that is classified as flooding. Brad Spurgeon Insurance Agency recommends that all coastal homeowners carry both windstorm and flood insurance to close this gap in protection.
Documentation and Claim Process
When a named hurricane hits, the speed and accuracy of your documentation can significantly impact your claim outcome. Insurance adjusters look for clear evidence of the cause of loss. If you have photos of your home before the storm, they serve as a baseline for comparison. During the storm, if it is safe to do so, documenting the path of debris or the direction of wind damage can help establish that the loss was wind-related rather than flood-related.
After the storm, you should file a claim as soon as it is safe to do so. Delaying the claim can complicate the investigation, as weather patterns and water levels change rapidly. Your insurance agent can guide you through the initial steps, including how to contact the carrier and what information to have ready. At Brad Spurgeon Insurance Agency, we assist clients with the claim process, ensuring that you communicate effectively with your carrier and understand your rights as a policyholder.
Key Takeaways
- Windstorm insurance covers physical damage to your home and contents caused by high winds, not water damage.
- Flood damage is excluded from windstorm policies and requires a separate flood insurance policy.
- Windstorm deductibles are often calculated as a percentage of the dwelling coverage amount.
- Documentation of the cause of loss is critical for a successful claim after a named hurricane.
- Homeowners in the Texas Gulf Coast should carry both windstorm and flood insurance for comprehensive protection.
- Your insurance agent can help you understand the specific terms and exclusions of your policy.
Frequently Asked Questions
Does windstorm insurance cover roof damage from a hurricane?
Yes, windstorm insurance typically covers roof damage caused by high winds or wind-driven debris. This includes shingles, tiles, and structural components of the roof. However, if the roof damage is due to water seepage from a pre-existing leak, it may not be covered.
What is the difference between windstorm and flood insurance?
Windstorm insurance covers damage caused by high winds, while flood insurance covers damage caused by rising water or heavy rain. These are two separate policies, and having one does not automatically include the other. Homeowners in coastal areas should consider carrying both.
How are windstorm deductibles calculated?
Does my windstorm policy cover personal property?
Yes, most windstorm policies include coverage for personal property, such as furniture, electronics, and clothing, if they are damaged by wind or wind-driven debris. The amount of coverage is typically a percentage of the dwelling coverage amount.
What should I do if my home is damaged by a named hurricane?
First, ensure your safety and the safety of your family. Then, document the damage with photos and videos. Contact your insurance agent to file a claim. Your agent can guide you through the process and help you communicate with your carrier.
Can I buy windstorm insurance after a hurricane is named?
No, most insurance companies have a moratorium period during which you cannot purchase new windstorm insurance or increase your coverage. This period typically begins when a hurricane is named or when a tropical storm warning is issued. It is important to have your policy in place before the storm season begins.Where can I get help with my windstorm insurance in Galveston?
Brad Spurgeon Insurance Agency provides expert guidance on windstorm and flood insurance for homeowners in Galveston and Texas City. We can help you understand your coverage, review your policy, and assist with the claim process.