Understanding Coverage Limits and Deductibles for Texas Wind & Hail Insurance
Homeowners in the Texas Gulf Coast face unique peril. Standard homeowners policies often exclude wind and hail damage, leaving property owners vulnerable to catastrophic financial loss. Windstorm insurance is a specialized policy type designed to cover structural damage caused by high winds and hail, which is distinct from standard homeowners coverage. According to recent industry data, over 60% of coastal homeowners in Texas lack adequate windstorm coverage, exposing them to significant risk during hurricane season. This guide explains how coverage limits and deductibles function in this specific market, helping you protect your asset effectively.
What Are Coverage Limits?
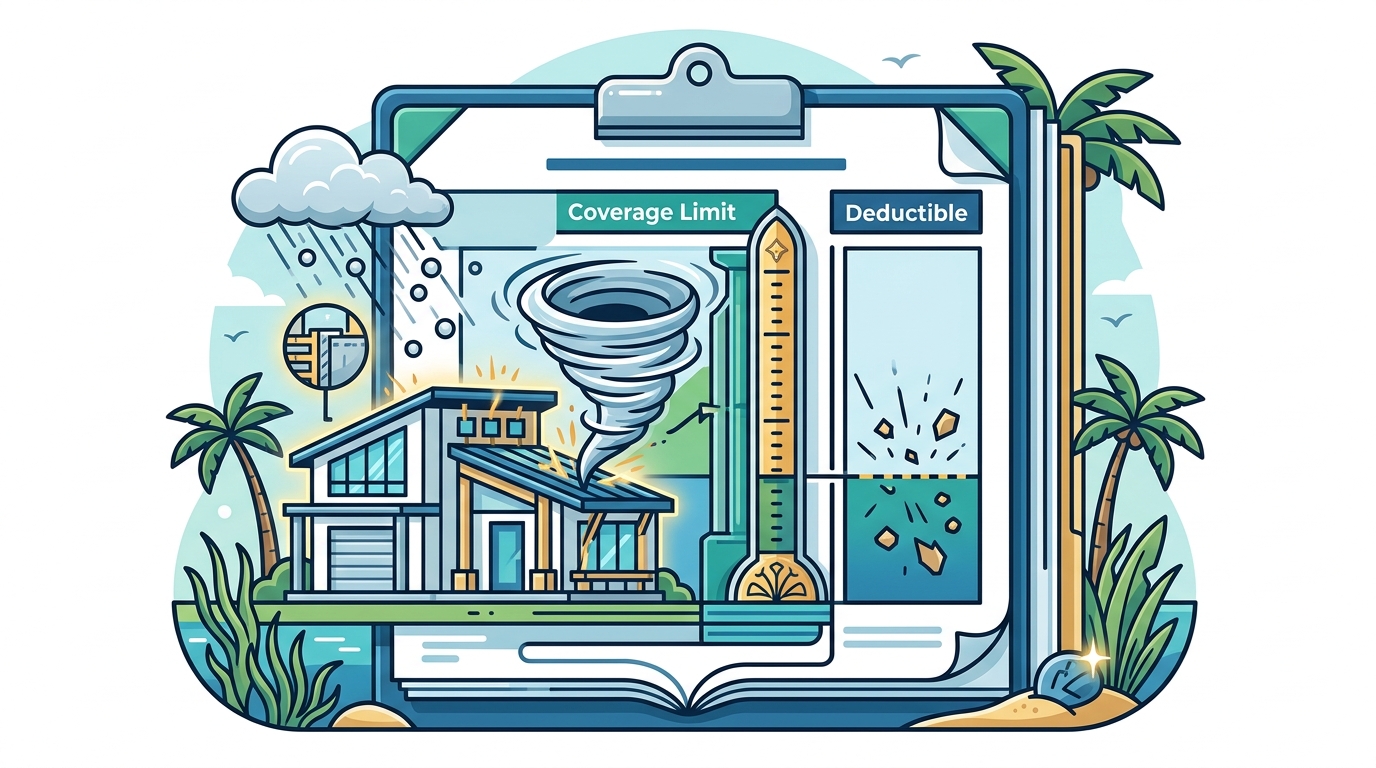
A coverage limit is the maximum amount an insurance company will pay for a covered loss. In the context of Texas wind and hail insurance, this limit applies to the physical structure of your home. If your home is destroyed by a hurricane, the policy will not pay more than the stated limit, regardless of the actual reconstruction cost.
Replacement cost value is the amount needed to rebuild your home with similar materials and quality. It does not account for land value or depreciation. For many homeowners in Texas City and Galveston, the standard limit of $100,000 or $250,000 is insufficient. Reconstruction costs in coastal Texas have risen significantly due to labor shortages and material inflation. You must ensure your limit matches the current cost to rebuild, not the market value of your home.
When selecting a limit, consider the following factors:
- Construction Type: Brick homes may have different repair costs than frame homes.
- Custom Features: High-end finishes, custom windows, and architectural details increase rebuild costs.
- Local Building Codes: Updated codes may require more expensive materials during reconstruction.
Brad Spurgeon Insurance Agency Inc. specializes in helping clients determine the correct limit for their specific property. We analyze your home's unique characteristics to ensure you are not underinsured. Visit our Home Insurance page to learn more about our tailored approach.
Types of Deductibles Explained
A deductible is the amount you pay out of pocket before your insurance coverage kicks in. In the Texas Gulf Coast region, deductibles for wind and hail damage often differ from standard homeowners policy deductibles. Understanding these differences is critical for financial planning.
Percentage-Based Deductibles
Most windstorm policies in Texas use a percentage-based deductible. This is calculated as a percentage of your dwelling coverage limit. For example, if you have a $300,000 coverage limit and a 2% deductible, you would pay $6,000 out of pocket before insurance pays the rest. This structure aligns the deductible with the size of the policy, ensuring that larger policies have proportionally larger deductibles.
Windstorm deductibles are typically higher than standard homeowners deductibles to reflect the elevated risk of coastal storms. Common percentages range from 1% to 5%. A 2% deductible is standard for many policies, but some high-risk areas may require 3% or more. It is essential to choose a deductible you can comfortably afford in the event of a claim.
Flat-Rate Deductibles
Some policies offer a flat-rate deductible for wind and hail damage. This is a fixed dollar amount, such as $1,000 or $2,500, regardless of the coverage limit. Flat-rate deductibles are less common in high-risk coastal zones but may be available for properties further inland or in lower-risk categories.
Choosing between a percentage-based and a flat-rate deductible depends on your coverage limit and risk tolerance. A higher deductible usually results in lower premium costs. However, you must be prepared to pay that amount if a storm occurs. Our team at Brad Spurgeon Insurance Agency Inc. can help you model these costs to find the right balance.
Windstorm vs. Flood Coverage
Many homeowners confuse windstorm damage with flood damage. These are two distinct perils with separate insurance requirements. Standard homeowners policies do not cover flood damage. Even if wind causes a roof to fail and rain enters your home, the resulting water damage is often considered flood-related if the water originates from outside.
Flood insurance provides coverage for property damage caused by flooding, which is defined as a general and temporary condition of partial or complete inundation of two or more acres of normally dry land or two or more properties. This definition is strict and excludes water damage from internal sources like burst pipes.
| Feature | Windstorm Insurance | Flood Insurance |
|---|---|---|
| Covered Peril | High winds, hail, tornadoes | Rising water, storm surge, heavy rain |
| Policy Source | Private carriers or Texas Windpool | National Flood Insurance Program (NFIP) |
| Deductible Type | Percentage-based (1-5%) | Flat-rate ($1,000-$5,000+) |
| Waiting Period | Usually 10-30 days | 30 days for new policies |
It is crucial to have both types of coverage if you live in a coastal area. Wind can cause structural damage, while flood can destroy the foundation and interior. We offer comprehensive Flood Insurance quotes to ensure your property is fully protected against all water-related risks.
Calculating Your Coverage Needs
Determining the right coverage limit and deductible requires a careful analysis of your property and financial situation. Here is a step-by-step process to help you make an informed decision.
Step 1: Assess Reconstruction Costs
Do not rely on your property tax assessment or market value. These figures often do not reflect the true cost to rebuild. Use a professional estimator or consult with a local contractor to get an accurate reconstruction cost. In Texas, construction costs vary significantly by county and city.
Step 2: Evaluate Your Risk Profile
Consider your home's location relative to the coast. Properties in Galveston, Texas City, and other Gulf Coast communities face higher wind and flood risks. Higher risk areas may require higher coverage limits and potentially higher deductibles. Our agency serves Texas City and all Texas Gulf Coast communities with specialized knowledge of local risks.
Step 3: Choose a Comfortable Deductible
Review your emergency savings. Can you afford a $10,000 deductible if a storm hits? If not, you may need a lower coverage limit or a different policy structure. Remember that a higher deductible lowers your premium, but it increases your out-of-pocket risk.
Step 4: Review Policy Exclusions
Read the fine print. Some policies exclude certain types of hail damage or have specific requirements for roof age. Ensure you understand what is and is not covered. We provide Policy Review services to help you understand your current coverage gaps.
Policy Options and Providers
In Texas, windstorm insurance is available through private carriers and the Texas Windpool. The Texas Windpool is a residual market mechanism that provides coverage when private insurers withdraw from the market. However, private carriers often offer more comprehensive coverage and better customer service.
Brad Spurgeon Insurance Agency Inc. works with multiple top-rated carriers to find the best policy for your needs. We also offer a new Windstorm Included Home Policy for Texas Gulf Coast homeowners, which simplifies the process by bundling wind coverage with your homeowners policy.
Benefits of Working with a Local Agency
- Expertise: We understand the nuances of Texas insurance laws and regulations.
- Claims Support: We assist with Report a Claim processes to ensure fair and timely settlements.
- Personalized Service: We tailor policies to your specific needs, not just standard templates.
If you are not thrilled with your current insurance, contact us today. We can help you find a better solution. Visit our Quotes page to get started.
Key Takeaways
- Windstorm insurance is a specialized policy type designed to cover structural damage caused by high winds and hail, which is distinct from standard homeowners coverage.
- Coverage limits must reflect the current replacement cost value, not the market value of your home.
- Deductibles in Texas are often percentage-based, ranging from 1% to 5% of the dwelling coverage limit.
- Flood insurance is separate from windstorm insurance and is required in many coastal zones.
- Brad Spurgeon Insurance Agency Inc. has served the Gulf Coast since 1986, providing trusted insurance advice for over 35 years.
- Our agency offers a new Windstorm Included Home Policy for simplified coverage.
- Always review your policy exclusions and ensure you understand what is covered.
Frequently Asked Questions
What is the difference between windstorm and flood insurance?
Windstorm insurance covers damage from high winds and hail, such as roof damage or broken windows. Flood insurance covers damage from rising water, including storm surge and heavy rain that inundates the property. Standard homeowners policies typically exclude flood damage.
How is a windstorm deductible calculated?
A windstorm deductible is usually a percentage of your dwelling coverage limit. For example, a 2% deductible on a $300,000 policy means you pay $6,000 out of pocket. This is different from a flat-rate deductible used in some other types of insurance.
Do I need windstorm insurance if I live in Texas City?
Yes, if you live in Texas City or any coastal community, you likely need windstorm insurance. Standard homeowners policies in Texas often exclude wind and hail damage. Our agency specializes in Home Insurance for these specific risks.
What is the Texas Windpool?
The Texas Windpool is a residual market mechanism that provides windstorm insurance when private carriers withdraw from the market. It is a last-resort option for homeowners who cannot find coverage elsewhere.
How can I get a quote for windstorm insurance?
You can get a quote by visiting our Quotes page or contacting us directly. We offer free consultations to help you understand your options and find the best coverage for your needs.
What is the new Windstorm Included Home Policy?
This is a new policy option offered by Brad Spurgeon Insurance Agency Inc. that bundles windstorm coverage with your homeowners policy. It simplifies the insurance process and ensures you have comprehensive protection against coastal risks.
How do I report a claim?
You can report a claim through our Report a Claim portal or by contacting our office. We are here to help you navigate the claims process and ensure you receive fair compensation.
Protect Your Home Today
Do not wait for a storm to hit before reviewing your insurance coverage. Ensure you have the right limits and deductibles to protect your home and family. Contact Brad Spurgeon Insurance Agency Inc. for a free consultation. We are here to help you navigate the complexities of Texas wind and flood insurance.
Get a Free Insurance Quote today and secure your peace of mind.