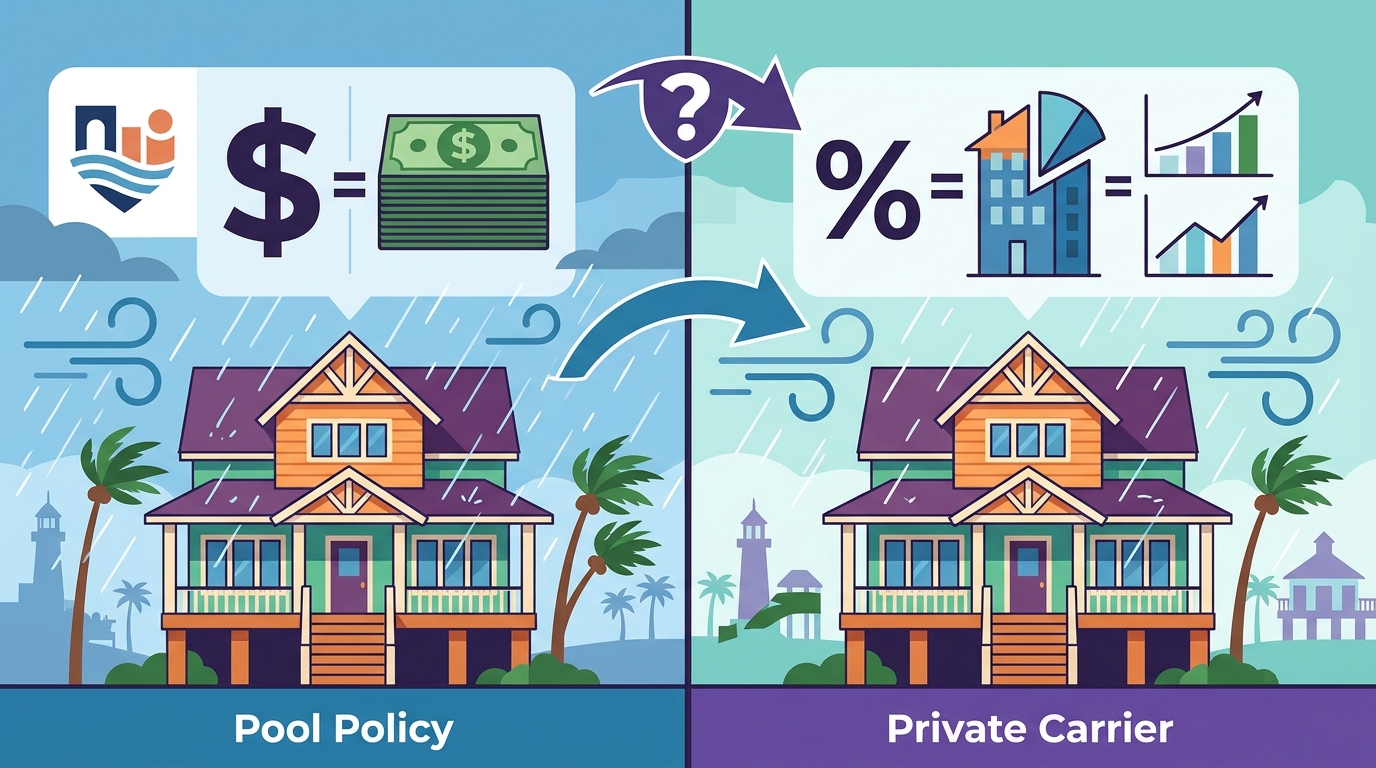
Named storm deductibles in Texas function differently depending on whether your policy is issued by a state-run pool like TWIA or a private carrier. Pool policies typically use a fixed dollar amount, while private policies often use a percentage of the dwelling coverage. This distinction significantly impacts your out-of-pocket costs during hurricane season. Brad Spurgeon Insurance Agency helps Galveston homeowners navigate these differences to ensure they understand their true financial exposure before a storm makes landfall.
Understanding State Pool Deductible Structures
Private Carrier Percentage-Based Deductibles
This percentage model aligns the deductible with the value of the home. As home values increase, the deductible increases proportionally. This structure is designed to reduce the frequency of small claims and keep premiums lower for the carrier. For high-value properties, the percentage deductible can result in a significantly higher out-of-pocket cost compared to a fixed pool deductible. Homeowners must ensure they have sufficient emergency funds to cover this potential liability.
Comparing Financial Impact on Homeowners
Another factor is the scope of the deductible. Some private policies apply the named storm deductible to both wind and flood damage, while others separate them. Flood insurance typically has a separate deductible. Homeowners must review their policy declarations page carefully to understand which perils are covered under the named storm deductible. This clarity is essential for budgeting and financial planning.
Selecting the Right Deductible for Your Home
Choosing the right deductible requires balancing premium costs with potential out-of-pocket expenses. A higher deductible usually results in a lower premium, but it increases the financial risk during a storm. Homeowners should assess their emergency savings and overall financial resilience. If you have limited savings, a lower deductible may be worth the higher premium. If you have substantial savings, a higher deductible can reduce your annual insurance costs.
Location also plays a role in this decision. Homes closer to the coast may face higher wind risks, making the deductible structure more critical. Brad Spurgeon Insurance Agency works with clients in Texas City and Galveston to evaluate these factors. We help you compare fixed and percentage deductibles based on your specific home value and financial situation. This personalized approach ensures you are not overpaying for coverage you do not need or underinsured for risks you cannot afford.
Key Takeaways
- State pool deductibles are typically fixed dollar amounts, while private policies often use percentages of dwelling coverage.
- A fixed deductible provides predictability but may be disproportionately low for high-value homes.
- Percentage deductibles scale with home value, potentially resulting in higher out-of-pocket costs for expensive properties.
- Homeowners must ensure they have sufficient emergency funds to cover their specific deductible amount.
- The scope of the deductible, including whether it applies to flood damage, varies by policy and carrier.
- Consulting with an insurance professional helps align deductible choices with your financial resilience and home value.
Frequently Asked Questions
What is a named storm deductible?
A named storm deductible is the amount a homeowner must pay out of pocket for wind and hail damage caused by a named hurricane or tropical storm before insurance coverage begins.
How do TWIA deductibles differ from private carrier deductibles?
TWIA deductibles are usually fixed dollar amounts, while private carriers often use a percentage of the dwelling coverage limit. This means private deductibles increase as home value increases.
Can I change my named storm deductible?
Yes, you can often change your deductible when renewing your policy or during the policy period, subject to carrier approval. Changing the deductible will affect your premium.
Does the named storm deductible apply to flood damage?
Generally, no. Flood damage is covered under a separate flood insurance policy, which has its own deductible. You must check your specific policy terms to confirm.
How much should I have in savings for a deductible?
Where can I get help comparing these policies?
You can contact Brad Spurgeon Insurance Agency for a free consultation to compare pool and private windstorm options for your specific property.
Conclusion
Understanding the difference between fixed and percentage-based named storm deductibles is essential for Texas coastal homeowners. The choice between a state pool and a private carrier has significant financial implications that extend beyond the annual premium. By evaluating your home value, financial reserves, and risk tolerance, you can make an informed decision that protects your investment. Brad Spurgeon Insurance Agency is committed to helping you navigate these complexities with clarity and confidence. To discuss your options, schedule a free consultation. Learn more: Best Lago Mar Homeowners.