7 State Residual Market Options for Commercial Windstorm Coverage
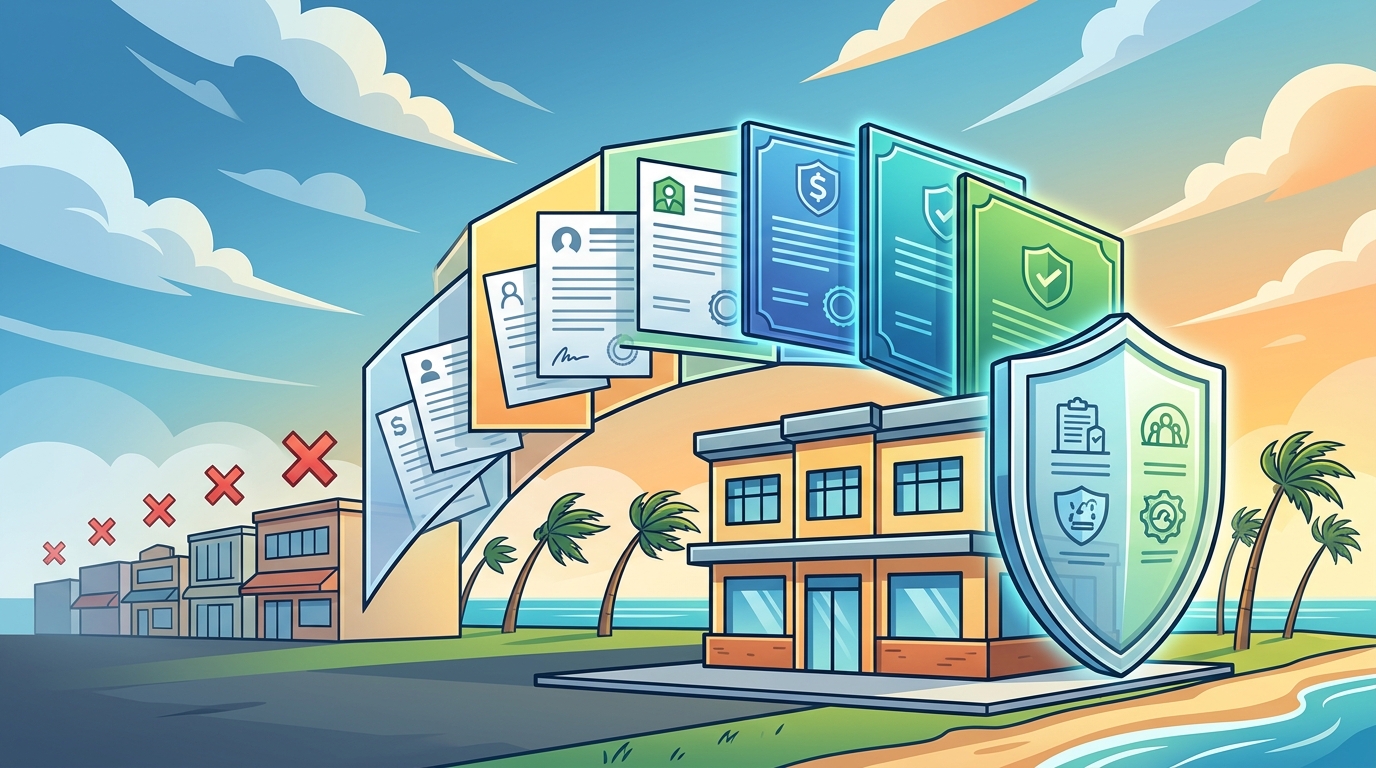
When traditional insurance carriers issue a notice of non-renewal for commercial windstorm coverage, business owners often face a critical gap in protection. State residual markets serve as the final line of defense, providing essential coverage when the voluntary insurance market withdraws. These specialized programs ensure that high-risk properties in coastal and hurricane-prone regions can still secure the financial safety net required for continued operations. Understanding these options is vital for Texas business owners navigating the complexities of the Gulf Coast insurance landscape. according to Residual Market Plans For additional details, review the Best Lago Mar Homeowners.
1. Texas Windstorm Insurance Association (TWIA)
Primary state residual market for Texas coastal windstorm coverage. The Texas Windstorm Insurance Association is the state's designated residual market for windstorm insurance. It provides coverage to property owners in designated coastal counties when they cannot obtain coverage from the voluntary market. TWIA policies are mandatory for eligible properties in the designated area if the voluntary market is unavailable. according to What Utah s
2. FEMA National Flood Insurance Program (NFIP)
Federal residual market for flood-related commercial losses. The National Flood Insurance Program is a federal program that provides flood insurance to property owners in participating communities. While primarily known for residential coverage, it also offers commercial flood insurance. This program acts as a residual market when private insurers decline to cover flood risks, particularly in high-risk zones. according to How Federal Spending
3. State-Specific Commercial Property Funds
State-backed funds for high-risk commercial properties. Some states operate specific funds or pools designed to cover commercial properties that are deemed too risky for the voluntary market. These funds often focus on specific perils like wind or flood and are regulated by the state insurance department. They provide a structured alternative for businesses that have been non-renewed by private carriers.
4. Regional Windstorm Pools
Multi-state or regional pools for shared risk management. Regional windstorm pools allow multiple states or insurers to share the risk of catastrophic wind events. These pools can provide coverage options for businesses in areas where individual state markets may be strained. They often offer more flexible terms and broader coverage options than single-state residual markets.
5. Surplus Lines Market
Specialized market for high-risk or unusual commercial risks. The surplus lines market is a specialized segment of the insurance industry that provides coverage for risks that are not available in the standard market. This market is often the first alternative for businesses that have been non-renewed by traditional carriers. It offers a wide range of policies from various carriers, providing flexibility in coverage terms and limits.
6. Private Excess and Surplus Carriers
Private carriers specializing in high-risk commercial properties. Private excess and surplus carriers are insurance companies that write policies for risks that are not available in the standard market. These carriers often have more underwriting flexibility and can provide coverage for businesses with unique risk profiles. They are a key component of the residual market ecosystem, offering competitive rates and tailored coverage options.
7. Hybrid Public-Private Programs
Collaborative programs combining public and private resources. Hybrid public-private programs combine the stability of state-backed residual markets with the efficiency of private insurance carriers. These programs often provide a more sustainable long-term solution for high-risk properties. They can offer better pricing and service levels than pure residual markets while maintaining the safety net of state support.
Choosing the Right Residual Market Option
Selecting the appropriate residual market option depends on your specific risk profile, location, and coverage needs. Consider factors such as the type of peril, the size of your property, and the availability of coverage in your area. Consulting with an experienced insurance agent can help you navigate these options and find the best fit for your business.
Frequently Asked Questions
What is a state residual market?
A state residual market is a government-backed insurance program that provides coverage to individuals and businesses who cannot obtain insurance from the voluntary market. It acts as a last resort for high-risk properties. according to What Utah s
How does TWIA work for commercial properties?
TWIA provides windstorm coverage to eligible commercial properties in designated coastal counties in Texas when they cannot obtain coverage from the voluntary market. It is a state residual market that ensures access to insurance for high-risk properties.
Can I get flood insurance from a state residual market?
Yes, the FEMA National Flood Insurance Program is a federal residual market that provides flood insurance to commercial properties. It is available to property owners in participating communities, including those in high-risk flood zones.
What is the difference between a residual market and a surplus lines market?
A residual market is a government-backed program that provides coverage when the voluntary market is unavailable. A surplus lines market is a private market that provides coverage for high-risk or unusual risks. The surplus lines market is often the first alternative for businesses that have been non-renewed by traditional carriers.
How can I find a residual market option for my business?
Consult with an experienced insurance agent who can help you navigate the available options. They can assess your risk profile and recommend the best residual market or surplus lines option for your business.
Is residual market coverage more expensive than voluntary market coverage?
Residual market coverage can be more expensive than voluntary market coverage, but it is often the only option available for high-risk properties. The cost depends on the specific program and the risk profile of the property.