Galveston Homeowners Guide to the National Flood Insurance Program
Galveston homeowners should know that the National Flood Insurance Program (NFIP) is the primary source of federal flood coverage, but local risk factors and premium structures require careful review. Brad Spurgeon Insurance Agency helps residents navigate these federal policies to ensure adequate protection for their coastal properties. For additional details, review the privatewindstorm com.
Understanding the Federal Framework
The National Flood Insurance Program (NFIP) is a federal program created to provide affordable flood insurance to residents in participating communities. It was established with the passage of the National Flood Insurance Act of 1968, marking a significant shift in how the United States manages flood risk. This program is administered by the Federal Emergency Management Agency (FEMA) and serves as the backbone of flood protection for millions of households. For additional details, review the .
For residents in Galveston, understanding this framework is essential because standard homeowners policies typically exclude flood damage. The NFIP fills this critical gap by offering coverage that is otherwise unavailable in the private market for many coastal areas. Congressional research confirms that the NFIP remains the primary source of flood insurance coverage for residential properties in the United States. For additional details, review the Customer Experience.
Eligibility and Community Participation
Eligibility for NFIP coverage depends on whether your community participates in the program. Galveston is a participating community, which means residents can purchase federal flood insurance. However, where you live determines if you can get government-backed flood insurance, so verifying your specific address is a crucial first step. FEMA's eligibility guidelines provide the definitive criteria for policy availability. For additional details, review the Frequently Asked Questions.
Risk Rating and Premium Structures
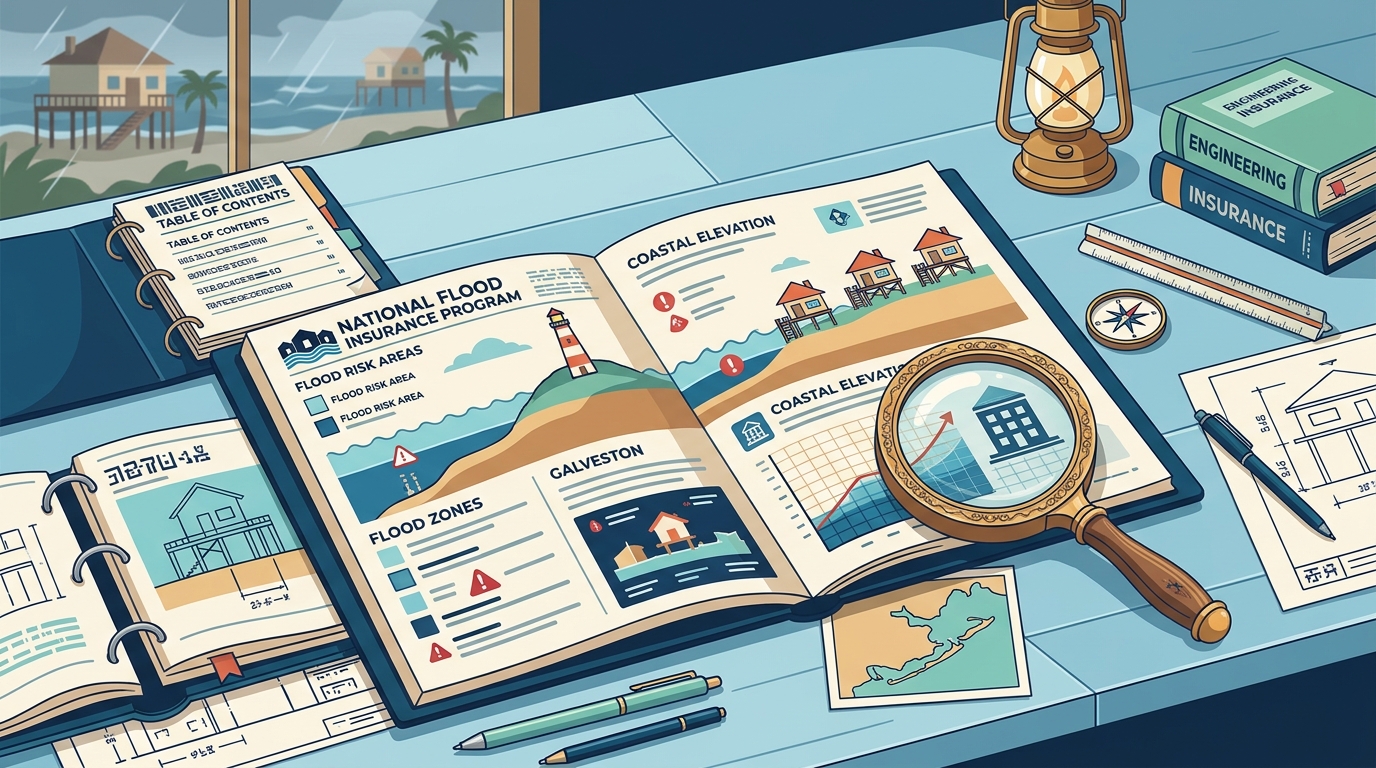
Flood insurance premiums are not uniform; they are calculated based on specific risk factors. The current rating structure, known as Risk Rating 2.0, moved away from a simple zone-based system to a more granular approach. This system considers factors such as the building's elevation, construction type, and the frequency of flooding in the area. For additional details, review the About.
Many stakeholders have expressed concern about the perceived affordability of flood insurance premiums, particularly as risk assessments become more precise. Recent analyses highlight that while premiums reflect true risk, they can be a significant financial burden for some homeowners. Understanding how your specific property is rated helps you anticipate costs and plan your budget accordingly.
The Impact of Coastal Geography
Galveston's unique geography, with its low elevation and proximity to the Gulf of Mexico, inherently influences flood risk ratings. Properties in this region often face higher premiums due to the increased likelihood of storm surge and tidal flooding. Homeowners should review their specific risk rating to understand why their premium is set at a particular level.
Coverage Options and Limits
Choosing the Right Deductible
Policyholders can choose from various deductible levels, which directly impact their premium costs. A higher deductible generally results in a lower premium, but it also means the homeowner pays more out of pocket in the event of a claim. Selecting the right deductible requires balancing upfront costs with potential financial exposure during a flood event.
Local Considerations for Galveston Residents
Living in Galveston presents unique challenges that go beyond standard flood risk. The city's history with hurricanes and its coastal location mean that residents must be prepared for both riverine and coastal flooding. Local infrastructure, such as seawalls and drainage systems, plays a role in mitigating risk, but it does not eliminate the need for insurance.
Homeowners in Galveston should also consider the impact of climate change on flood frequency and severity. As sea levels rise and storm patterns shift, the risk profile for coastal properties continues to evolve. Staying informed about local flood management initiatives and updating your insurance coverage accordingly is a prudent strategy for long-term protection.
Working with Local Experts
Navigating the complexities of the NFIP can be overwhelming, especially for first-time policyholders. Working with a local insurance agency that understands the specific risks of the Galveston area can make a significant difference. Brad Spurgeon Insurance Agency specializes in helping residents understand their options and select the most appropriate coverage for their unique situation.
Key Takeaways
- The NFIP is the primary source of federal flood insurance, established in 1968 and administered by FEMA.
- Eligibility depends on community participation, and Galveston is a participating community.
- Premiums are calculated using Risk Rating 2.0, which considers specific property and risk factors.
- Galveston's coastal geography and history with hurricanes influence local flood risk and premiums.
- Homeowners should review their specific risk rating and consider supplemental coverage if needed.
- Working with a local expert can help navigate the complexities of federal flood insurance.
Frequently Asked Questions
Is the National Flood Insurance Program available in Galveston?
Yes, Galveston is a participating community in the NFIP, which means residents can purchase federal flood insurance. Eligibility is determined by your specific address and community participation status.
What is the difference between building and contents coverage?
Building coverage protects the structure of your home, including the foundation and walls. Contents coverage protects your personal property, such as furniture and electronics, from water damage.
How are flood insurance premiums calculated?
Premiums are calculated using the Risk Rating 2.0 system, which considers factors like elevation, construction type, and flood frequency. This system provides a more accurate reflection of risk than previous zone-based methods.
Are there limits on NFIP coverage?
Can I buy flood insurance if I am not in a high-risk zone?
Yes, you can purchase flood insurance regardless of your flood zone. However, premiums in lower-risk zones are typically lower. It is always advisable to assess your specific risk before deciding on coverage.
How long does it take for a flood insurance policy to become effective?
There is typically a 30-day waiting period before a new flood insurance policy becomes effective. This waiting period does not apply if you are purchasing coverage during a declared flood event.
Does the NFIP cover wind damage?
No, the NFIP only covers flood damage. Wind damage is typically covered under a standard homeowners policy or a separate windstorm policy. Homeowners in coastal areas often need both types of coverage for comprehensive protection.
Protecting Your Home in Galveston
Understanding the National Flood Insurance Program is a critical step in protecting your home and family in Galveston. By knowing the eligibility requirements, coverage options, and premium structures, you can make informed decisions about your insurance needs. Brad Spurgeon Insurance Agency is committed to helping you navigate these complexities and find the right coverage for your property. today to discuss your flood insurance options and ensure your home is protected against the unique risks of coastal living.